What Does General Liability Insurance Cover for a Small Business?
Understand the third-party claims general liability can address, the limits and exclusions to check, and the risks that may need separate policies.
General Liability Per-Occurrence vs. Aggregate Limits Explained
A per-occurrence limit caps payment for covered injury or damage from one occurrence, an event as defined by the policy. An aggregate caps the total payments assigned to it over the applicable policy period. Both can restrict payment. A higher aggregate does not increase the amount available for a single occurrence.
Primary and Noncontributory vs. Waiver of Subrogation: Contract Insurance Terms Explained
Primary and noncontributory wording addresses which insurance responds first and whether it seeks contribution from another insurer. A waiver of subrogation addresses an insurer’s right to recover a payment from a specified party. These terms answer different questions, and a contract may request both. Confirm the supporting policy wording before saying either requirement is satisfied.
Additional Insured vs. Certificate Holder: What Is the Difference?
An additional insured and a certificate holder are not the same. A certificate holder is generally the party named to receive a certificate showing selected policy information. An additional insured may receive defined status under applicable policy wording or an endorsement, subject to the policy terms and the facts of the claim.
How to Meet Contract Insurance Requirements
Contract insurance requirements may ask for specific policy limits, certificate details, additional-insured status, endorsements, and policy wording before work starts. Compare what the contract requests with your actual policy documents so you can identify questions before you sign the agreement or send proof of coverage.
Premises Liability Insurance Coverage
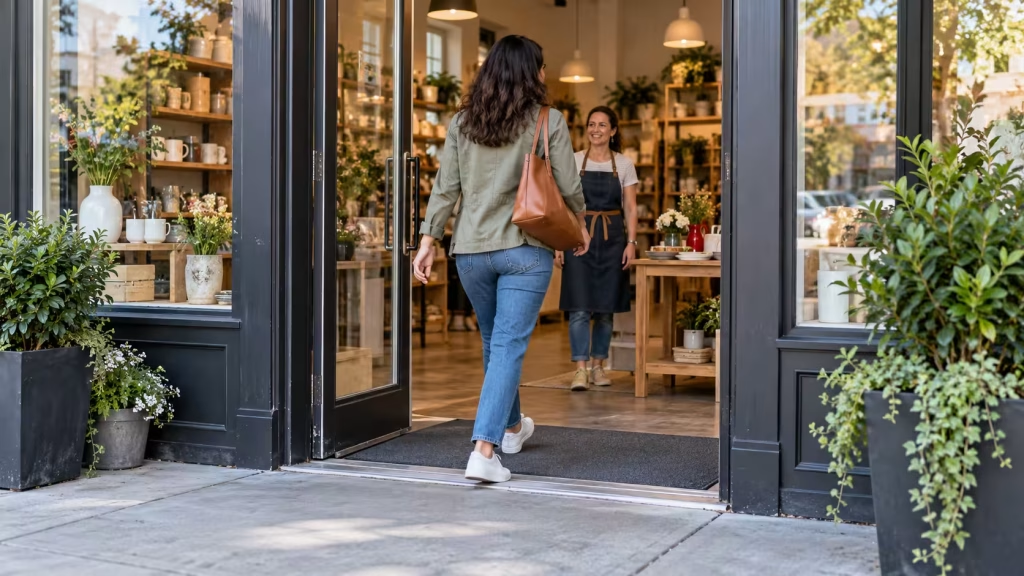
Premises liability insurance may help a business respond to covered claims that a customer or visitor was injured, or someone else’s property was damaged, because of conditions at its location. The applicable policy, exclusions, limits, and incident facts determine whether coverage applies.
Contractual Liability Insurance
A business contract can ask you to take responsibility for certain injuries, property damage, or losses. Contractual liability insurance may help with some liabilities your business assumes in a policy-defined insured contract, but it does not automatically cover every promise, delay, breach, or contract dispute. The answer depends on the contract language, the policy, any endorsements, the limits, and the facts of the claim.
What Is a COI and Why Is It Important?
A certificate of insurance is a short document that summarizes selected coverage details for one policy at a point in time. It helps a client, landlord, or general contractor verify what an insured carries, but it is evidence of insurance rather than the policy itself.