
Affordable insurance starts with an easy quote
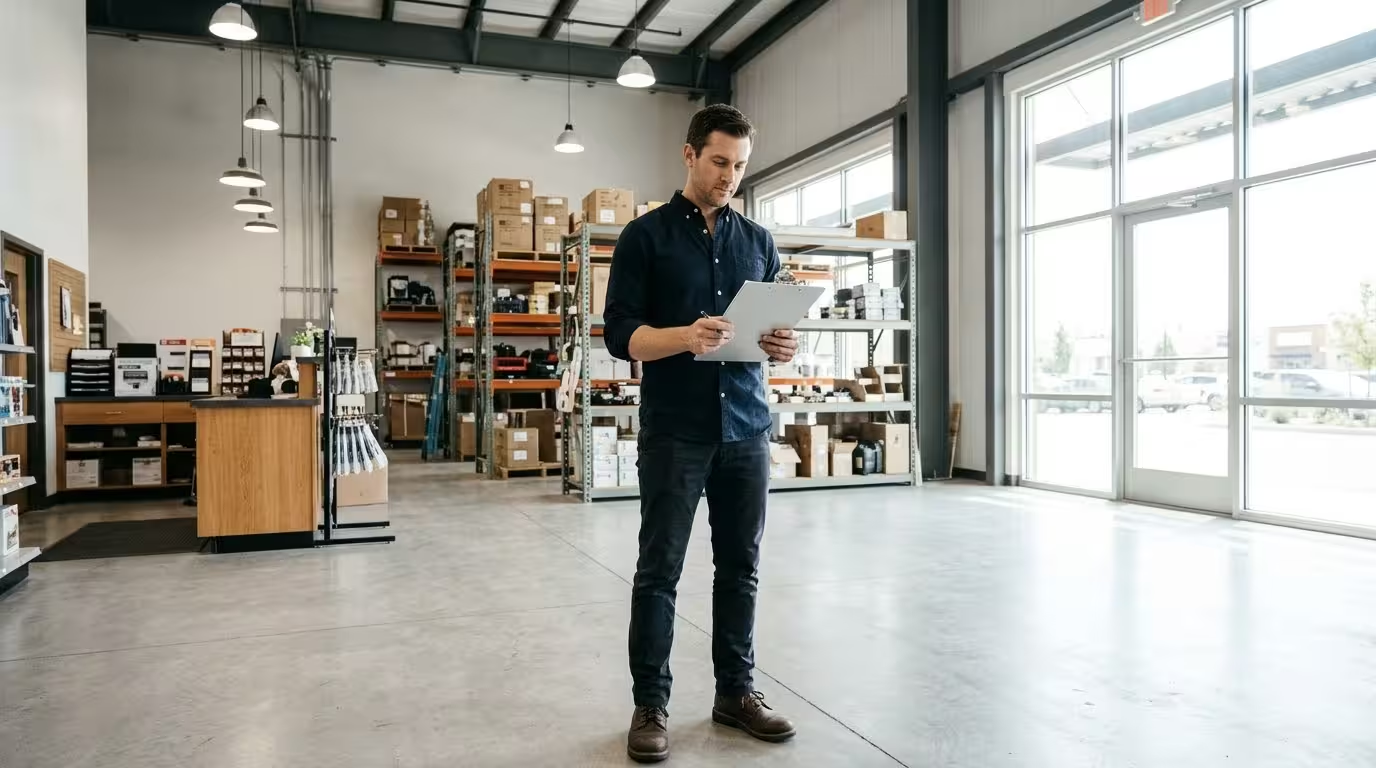
Commercial Property Insurance protects your building, inventory, furniture, and equipment at a scheduled address against fire, wind, hail, theft, and vandalism. Whether you own a standalone structure or lease a retail, office, or warehouse space, accurate limits keep one physical loss from halting daily operations.
A commercial property policy covers physical damage to owned buildings, permanent fixtures, business personal property, and equipment at your location. Standard policy forms outlined by the Insurance Information Institute divide coverage into structures and contents so you can match limits to what you own or must insure under a lease.
Standalone property coverage insures higher-value or specialized locations, while a BOP bundles liability and inland marine covers mobile gear off-site. Many business owners buy the wrong form because they assume one property policy follows tools to jobsites or includes third-party liability protection.
| Policy Type | Best Fit | What It Covers | Primary Limit or Gap to Watch |
|---|---|---|---|
| Standalone Commercial Property | Building owners, warehouses, manufacturers, and businesses with higher property values | Scheduled commercial buildings, business personal property, and optional business income | Excludes general liability and off-premises mobile equipment |
| Business Owner's Policy (BOP) | Eligible small offices, retail shops, and low-hazard service businesses | Bundles building and contents coverage, general liability, and business income in one policy | Carrier eligibility caps on square footage, building value, and trade class |
| Inland Marine Insurance | Contractors, mobile trades, and crews hauling tools or materials between jobsites | Tools, mobile equipment, and goods in transit or stored at temporary locations | Does not insure fixed commercial buildings or permanent warehouse stock |
When a small office or retail shop qualifies for bundled liability and property protection, compare a Business Owner's Policy against standalone property forms before deciding. When crews transport tools, compressors, or materials away from your main address, inland marine insurance fills the transit gap that fixed property forms leave open.
Replacement cost pays to repair or rebuild damaged property with similar new materials, while actual cash value subtracts depreciation from the claim payout. That valuation choice decides whether your claim check covers today's construction pricing or leaves you funding a large gap out of operating cash.
| Valuation Basis | How the Claim Pays | Premium Impact | Main Risk to Watch |
|---|---|---|---|
| Replacement Cost Value (RCV) | Pays current repair or replacement cost without deducting age or wear | Higher annual premium than ACV | Often pays ACV first and releases recoverable depreciation after repairs finish |
| Actual Cash Value (ACV) | Pays replacement cost minus physical depreciation for age and condition | Lower annual premium | Older roofs, HVAC systems, and machinery can lose half or more of their payout value |
Older commercial roofs frequently trigger underwriting inspections or mandatory ACV roof endorsements once a roof passes 15 to 20 years of age. Checking your valuation basis and roof settlement wording before renewal helps prevent an unexpected payout cut after a wind or hail storm.
Property coverage cost depends on rebuild value, construction type, occupancy hazard, local weather exposure, and fire protection upgrades. Because underwriters price each building individually rather than using flat rates, treat any general cost estimate as planning context, not a quote.
| Rating Factor | Why Underwriters Price It Closely | Practical Way to Prepare |
|---|---|---|
| Replacement Cost Valuation | Rebuilding limits reflect local labor, material, and debris-removal costs, not market sale price | Document square footage, roof age, electrical, plumbing, and HVAC update years |
| Construction Class (COPE) | Fire-resistive and masonry non-combustible buildings typically rate lower than frame structures | Confirm exact wall, roof, and structural framing details from inspection records |
| Occupancy and Neighboring Tenants | Cooking, woodworking, or flammable storage raises fire severity across multi-tenant buildings | List every operation conducted inside the structure, including neighboring tenant uses |
| Protection and Alarms | Proximity to fire hydrants, central-station alarms, and active sprinklers reduces loss severity | Gather current sprinkler inspection tags and central-station alarm certificates |
| Deductible and Coinsurance | Higher wind, hail, or all-peril deductibles lower premium, while 80 percent to 100 percent coinsurance enforces accurate limits | Match your deductible to cash reserves and verify limits against current rebuild costs |
State law rarely requires commercial building insurance, while mortgage lenders, SBA loans, and commercial landlords enforce strict property limits by contract. Confirming exact contract terms early keeps loan closings and commercial lease turnovers on schedule.
Dream Assurance reviews your declarations page, lease, or lender letter first, then compares commercial property insurance across multiple carriers. Our team checks valuation basis, coinsurance percentages, wind and hail deductibles, and optional business income limits side by side so you can spot gaps before coverage is put in place.
Bring your property address, square footage, roof and systems update years, inventory or equipment totals, and any lender or landlord insurance exhibits when you talk with our team. You can also see how building and contents protection connects with your broader business insurance coverage during one review.
Licensed in 30+ States: Dream Assurance serves clients in states where the agency and its producers hold or renew applicable insurance licenses. Coverage availability, carrier access, and policy options may vary by state, coverage type, underwriting requirements, and carrier appointment.
A commercial property policy covers owned buildings, permanently installed fixtures, business personal property, and equipment at a scheduled location. Policies typically protect against covered perils such as fire, lightning, windstorm, hail, theft, and vandalism, subject to your policy form and sublimits.
Yes, commercial tenants need property coverage because a landlord's building policy does not insure tenant inventory, equipment, furniture, or buildouts. Most commercial leases also require proof of business personal property and tenant improvements coverage before you receive the keys.
Replacement cost pays to repair or replace damaged business property with similar new materials, while actual cash value subtracts depreciation first. Choosing actual cash value lowers premium up front, but it can leave a large out-of-pocket gap when older roofs, machinery, or equipment are damaged.
Choose a BOP when your business qualifies for bundled property and liability; choose standalone coverage for higher values or specialized risks. Manufacturing plants, large warehouses, vacant buildings, and higher-hazard operations often need standalone property coverage or a Commercial Package Policy.
No, standard property policies exclude flood and earthquake damage unless you buy separate coverage or a dedicated endorsement. Businesses in flood zones, seismic areas, or high-value commercial corridors should review separate flood, earthquake, and sewer backup options before coverage is put in place.
A coinsurance clause reduces your claim payout if you insure your building or contents for less than the required percentage of replacement value. Most commercial property forms require 80 percent to 100 percent insurance-to-value, so reviewing current rebuild costs before renewal protects you from an underinsurance penalty.