Roofing contractor insurance helps roofing business owners review the liability, employee, vehicle, tool, property, and contract exposures that come with installation, re-roof, repair, and commercial roofing work. The right setup depends on how you operate, who performs the work, what you transport, and what your clients, lenders, or general contractors require.
Roofing business insurance often starts with general liability, and published pricing references from 2025 and 2026 put a solo owner-operator’s general liability between $1,500 and $3,000 a year, with a 10-to-20-worker operation closer to $7,000 to $15,000. Workers compensation adds more on top, priced per $100 of payroll. This page covers the coverage review, cost drivers, workers compensation, and contract requirements.
For roofing businesses, not homeowners: this page is written for roofing contractors and the companies that employ them. If you are a homeowner trying to understand whether insurance will pay for a roof repair, start with homeowners insurance instead.
Why roofing insurance is rated differently
Carriers classify roofing differently than most trades, and the difference shows up in what you pay, what carriers ask, and what contracts require. Three factors drive it.
Working at height is the first. According to the Occupational Safety and Health Administration, falls are among the most common causes of serious work-related injuries and deaths, and construction fall protection starts at six feet.
The injury record follows. The Bureau of Labor Statistics reports that roofers have one of the highest rates of injuries and illnesses of all occupations, as well as one of the highest rates of occupational fatalities.
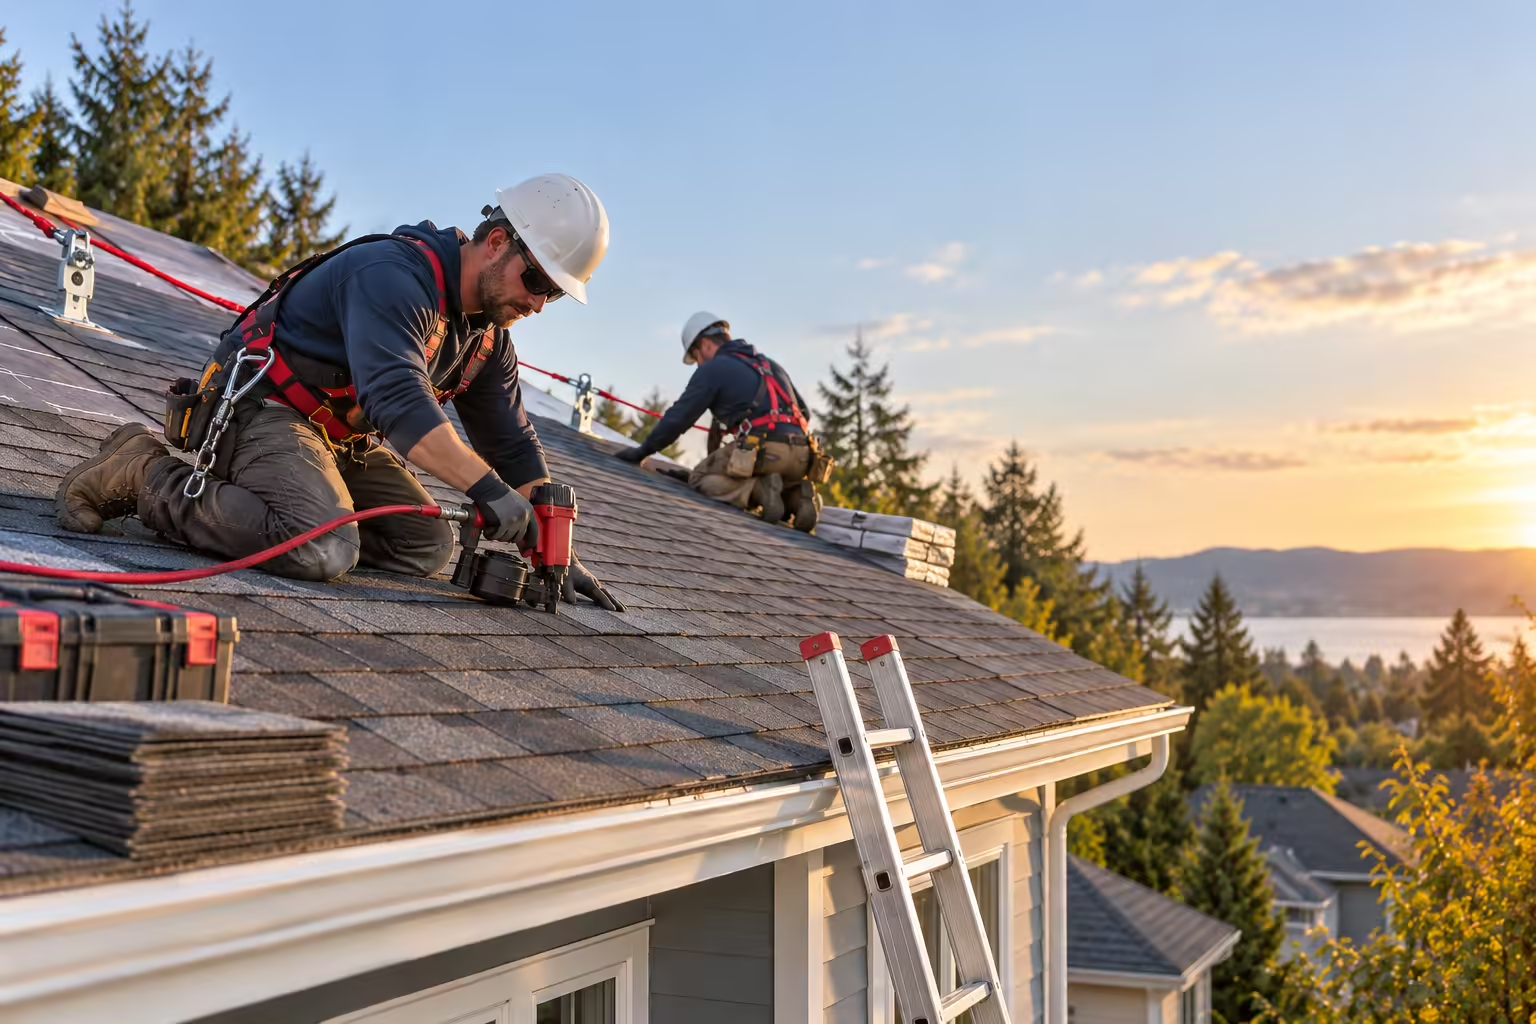
The work itself adds the third. Tear-offs send debris off the roof edge, and water intrusion from an unfinished job may not appear until months later. Finished-work claims are decided by the policy form and the timeline, so carriers price roofing for severity rather than volume.
Coverage to review for a roofing business
The coverage conversation starts with how you operate, not with a package name. Most roofing companies review some combination of the policies below, and none covers everything on its own. For general background on how these pieces fit together, the iii.org business insurance section is a useful orientation.
General Liability
General liability responds to third-party claims: bodily injury or property damage your work causes to someone else or their property. A roofing example: during a tear-off, debris dents a customer’s gutter and cracks a neighbor’s window. Most contracts require roofing liability insurance, and clients ask to see it on a certificate. Start with general liability insurance when you review limits and completed operations.
Workers Compensation
Workers compensation responds to work-related injuries and illnesses for your employees. Given roofing’s injury data, it is often the most important line you will price, and it has its own section below.
Commercial Auto
Commercial auto covers the vehicles your business uses for work: trucks, trailers, and the driving between jobs, suppliers, and dump sites. A roofing example: a loaded trailer in a collision. Business use of personal vehicles often needs hired or non-owned coverage. Review commercial auto insurance for work vehicles with the whole vehicle list.
Inland Marine and Tools
Inland marine coverage, sometimes called a tools and equipment floater, follows movable equipment instead of covering one fixed location. A roofing example: nail guns, compressors, and hoists stolen from a locked trailer overnight, or materials in transit.
Completed Operations
Completed operations is the part of liability coverage that answers for work you have already finished. A roofing example: a leak traced to flashing installed months ago. The timing and facts decide how it responds; the workmanship boundary is covered below.
Commercial Property or a Business Owner’s Policy
Commercial property covers what you own: the shop, the office, stored materials, and business personal property. For some roofing businesses, an eligible business owner’s policy coverage bundles property and liability in one form.
Umbrella or Excess Liability
Umbrella or excess liability adds limits above your underlying policies. Larger commercial projects often require limits higher than a standard package provides.
Roofing insurance coverage comparison
The table below is a planning aid, not a substitute for policy wording. Limits come from the policy and the contract, and underwriting varies by operation and state.
Coverage
What it helps with
Who typically reviews it
Limits to understand
General Liability
Third-party bodily injury and property damage, including completed operations
Every roofing contractor
Contracts often request $1M per occurrence and $2M aggregate; verify the work description
Workers Compensation
Covered work injuries and illnesses for employees
Any roofing business with employees (requirements vary by state)
Statutory benefits where required; priced per $100 of payroll
Commercial Auto
Business vehicles, trailers, and hired or non-owned use
Any operation driving for work
Liability plus optional physical damage; list every vehicle and driver
Tools and Equipment (Inland Marine)
Tools, equipment, and materials in transit or in temporary storage
Crews moving tools between jobs
Scheduled values or blanket limits; check transit and storage terms
Commercial Property or BOP
Your building, shop, stored materials, and business personal property
Businesses with a location or stored inventory
Replacement cost or actual cash value; check the BOP eligibility rules
Required underlying limits must be in place before the excess layer responds
What roofing insurance usually does not cover
The fastest way to be disappointed is to assume a policy covers more than it does. These three boundaries cause the most confusion.
Boundaries to confirm
Faulty workmanship. The cost of redoing your own defective work is typically excluded. If a crew installs the wrong underlayment and the roof must be reopened, the labor to fix your own mistake usually is not covered, though resulting damage to other property often is treated differently.
Employee injuries. General liability is not the policy for your own employees’ work injuries. Workers compensation and employer obligations handle that side of the exposure.
The completed-operations boundary. Coverage for finished work carries its own conditions and timing. When a leak appears long after completion, the response depends on the policy form, when the work was done, and what the contract says.
Every policy also carries exclusions specific to its form and class of work. The coverage review translates those into your operation’s language.
What roofing contractor insurance costs
There is no single price for roofing contractor insurance, and any quote that ignores your operation is guessing. Published pricing references from 2025 and 2026 show how wide the legitimate range is.
Business profile
Commonly cited annual range
Basis
Solo owner-operator (General Liability)
$1,500 to $3,000
Published industry pricing references, 2025 to 2026
Crew of 10 to 20 (General Liability)
$7,000 to $15,000
Published industry pricing references, 2025 to 2026
Any size (Workers Compensation)
Priced per $100 of payroll
Class-code rates; varies by state and payroll
Two structural facts sit behind those numbers. Roofing is a high-hazard class, so premiums commonly run three to ten times general contractor rates. Workers compensation is frequently the largest single line on a roofing invoice.
What moves your number up or down:
Roof type and material. Asphalt shingles, tile, metal, and flat systems carry different loss costs.
Pitch, height, and access. Steeper, taller roofs slow the work and raise the consequences of a slip.
Work mix. New construction, re-roofs, repairs, and the residential-to-commercial balance change project size, contracts, and required limits.
Payroll and subcontractors. Payroll sizes the operation; subcontracted volume, crew classification, and collected certificates change the review.
Claims history and experience. Prior losses follow the business into every renewal, and newer operations are priced while the record builds.
State and territory. Rates, class codes, and carrier appetite vary by where the work happens.
Limits, deductibles, and endorsements. Contract requirements and your deductible choice both move the premium.
If your work includes new construction or projects covered while they are being built, review builder’s risk insurance cost to see how project coverage is priced.
Roofing workers compensation
Roofing workers compensation insurance is the line most roofing owners feel first, and the coverage with the most moving parts. Understanding the mechanics before the quote saves money and surprises.
Premium is built on a formula that only looks simple: a rate per $100 of payroll, multiplied by the payroll assigned to each employee’s class code. Roofing class codes carry some of the highest rates in the system because the injury data behind them is severe, and the codes and rates are assigned state by state. The same crew can price differently across state lines, and none of it is negotiable.
Experience modification is the second lever. An experience modification, often called a mod or EMR, compares your loss history against other businesses in your class. A clean record lowers what you pay. A few expensive claims raise it, sometimes for years, which is why the loss runs at renewal matter.
The third lever is how your crews are paid, and it is where a lot of roofing quotes go wrong. W-2 employees’ payroll belongs in your workers compensation premium. Genuinely independent 1099 contractors with their own coverage are handled through certificates instead. If a crew is misclassified, a carrier audit can move those wages into the calculation after the fact.
One caution: requirements for carrying workers compensation vary by state and by workforce. Confirm the rule that applies to your operation.
Contracts and certificates: what general contractors and owners require
Most roofing work starts with a contract that includes insurance requirements. A property owner, general contractor, or lender asks for proof of coverage before work begins, and the wording matters more than most roofing offices expect.
A certificate of insurance is proof that certain coverage was reported when it was issued. It is not the policy itself and cannot change what the policy covers. When a contract asks for additional insured status, waiver of subrogation, primary and non-contributory wording, or specific limits, each phrase translates into forms and endorsements:
Additional insured: a person or organization added to your policy for certain liability protection required by a contract.
Waiver of subrogation: policy wording that limits your insurer’s ability to recover money from another party after paying a claim.
Primary and non-contributory: wording that asks your policy to respond first, ahead of another party’s coverage.
Before the next job starts, compare the exact request against the actual policy. A certificate holder is not automatically an additional insured, and a note typed onto a certificate cannot create coverage the policy does not provide.
Dream Assurance handles certificate requests through its service-center support. Existing clients can start standard requests through the self-service COI portal, and anything unusual should go to the team with the contract attached. For the coverage questions behind a request, start with certificate of insurance support.
What to gather before requesting a quote
A complete starting point helps an agent review the operation instead of treating it like a generic account. Bring the following:
Preparation checklist
ReviewBusiness and work details. Legal business name, locations and states where you work, years in business, revenue, and payroll.
CheckPeople and subcontractors. Employee count, job classifications, subcontractor use, written agreements, and certificates collected from other crews.
BringVehicles, tools, and property. Vehicle list and drivers, tool and equipment values, rented items, materials in transit, and storage locations.
ReviewCurrent insurance and history. Policy declarations, limits, deductibles, endorsements, prior claims and loss runs, and the renewal date.
CheckContract requirements. Client or general contractor specifications, certificate-holder details, requested additional insured wording, waiver language, and deadlines.
How Dream Assurance can help review the setup
Dream Assurance is an independent insurance agency that helps roofing businesses compare coverage options from multiple carriers and understand what changes between policies. We shop 30+ carriers and walk through the details with you.
Dream Assurance is licensed in 30+ states, and the agency serves clients where it and its producers hold or renew applicable insurance licenses. Coverage availability, carrier access, and policy options may vary by state, coverage type, underwriting requirements, and carrier appointment.
If you want to talk the details through first, talk with our team and bring your current policy and loss history.
Experience the confidence shared by the roofing businesses we protect, and let us help turn your operation's details into a clearer coverage review.
I've had a fantastic experience with Dream Assurance. From the very beginning, Kurtis made the process of choosing a plan straightforward and stress-free.
If you're looking for real people that handles your needs fast then dream assurance is the way to go. Micheal Moran is probably the best insurance agent I've ever had. No matter the time or day, he finds a way to respond back. Not to mention we're in two different time zones and he works like we're in the same state. I wish I could give them more stars. Forgot to mention they'll beat any insurance rates you find!!!
Roofing contractor insurance questions
What is roofing contractor insurance?
Roofing contractor insurance is a set of business policies that respond to roofing-specific risks: liability claims, employee injuries, vehicles, tools, and the property you own or store. Coverage depends on the forms and limits.
How much does roofing contractor insurance cost?
Published pricing references from 2025 and 2026 put a solo owner-operator's general liability between $1,500 and $3,000 a year, with a 10-to-20-worker operation closer to $7,000 to $15,000. Treat any range as planning context, not a quote.
Why is roofing insurance more expensive than other trades?
Roofing combines working at height, heavy tear-off work, and damage that may not appear for months. Carriers price for that severity, so roofing runs above interior trades, and roofing class codes are among the highest in workers compensation.
Do roofers need workers compensation insurance?
Requirements vary by state and by workforce, so the answer depends on your setup. Even where it is not mandatory, most roofing businesses with employees carry it. Confirm the rule that applies to your setup.
Should I carry workers comp if it is not required?
Many roofing businesses do, because one serious injury changes the math quickly. Without workers compensation, an employee injury can become a lawsuit against the business. An agent can show what the coverage costs against that exposure.
How do 1099 crews versus W-2 employees affect my workers comp premium?
Directly. W-2 payroll is included in your workers compensation premium at the class rate. Genuinely independent 1099 contractors with their own coverage are handled through certificates instead.
Is general liability enough for a roofing contractor?
General liability is the foundation, not the whole program. It responds to third-party injury and property damage claims, but not employee injuries, your vehicles, your tools, or your own property.
Does general liability cover a roof leak after the job is finished?
Possibly, and the details decide it. Finished-work claims fall under the completed operations part of the policy, and the policy form, timing, and cause all matter.
How fast can I get a certificate of insurance?
Timing depends on the request and your policy. Existing clients can start standard certificate requests through the self-service COI portal. Special wording or unusual requirements should go to the team with the contract attached.
Can I get roofing insurance as a new contractor with no prior coverage?
New operations can usually find coverage, though the market works differently for them. Without loss history, pricing reflects that, and not every carrier writes brand-new roofing companies. An agent can compare the options.
Prefer to talk it through first? Call 618-657-7525.
Coverage Guidance That Meets You Where You Are
Headquartered in Overland Park, KS and serving clients across multiple states, our team provides straightforward guidance to help you make informed insurance decisions.
If you're comparing insurance options or reassessing your current coverage, we'll help you evaluate what you have, identify potential gaps, and find a path forward that makes sense for your situation.
Licensed In 30+ States
Headquartered in Overland Park, KS, with licensed support across the Midwest, South, Northeast, and West.
AL, AZ, AR, CA, CO, DE, FL, GA, IL, IN, IA, KS, KY, MI, MN, MS, MO, MT, NE, NV