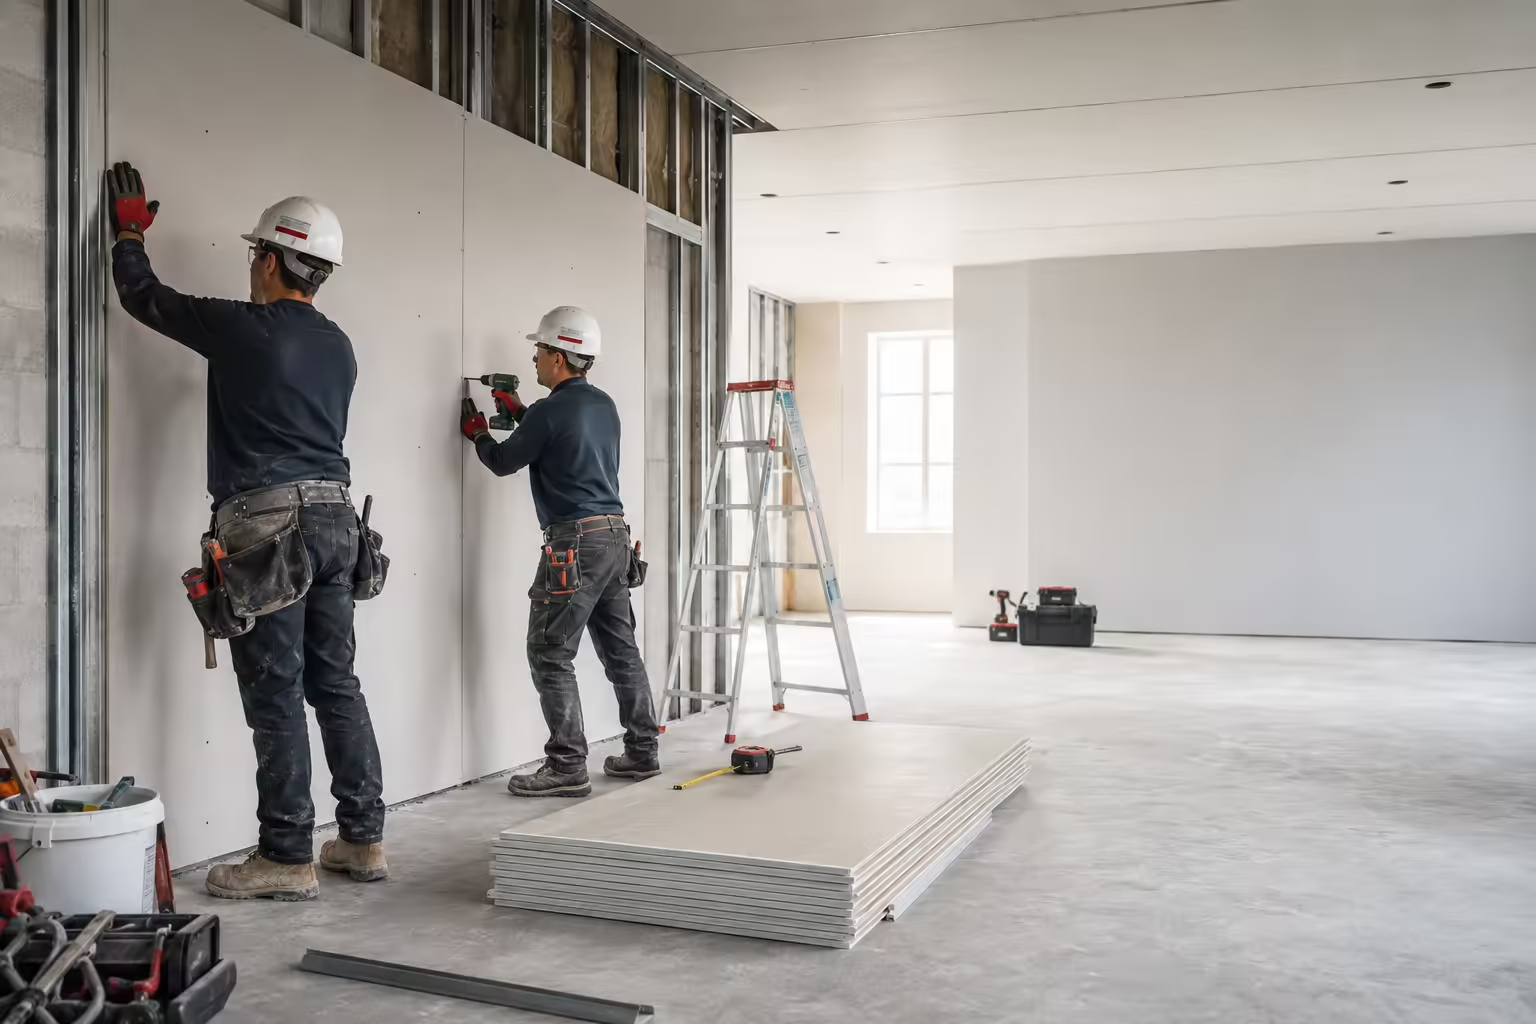
Drywall contractor insurance helps business owners review the liability, employee, vehicle, tool, property, and contract exposures that come with drywall installation, finishing, repair, and remodeling work. The right setup depends on how you operate, who performs the work, what you transport, and what your clients or general contractors require.
Simply put, there is no single policy that automatically handles every drywall business risk. A useful review starts with the work you perform, then connects the coverage to your employees, subcontractors, vehicles, tools, property, and contract requirements.
Why drywall contractors review more than general liability
General liability is an important starting point for third-party bodily injury, property damage, and certain personal or advertising injury claims. It does not automatically cover employee injuries, the tools in your van, a vehicle used for business, or every dispute about the quality of your work.
A drywall contractor may also need to review workers' compensation, commercial auto, tools and equipment or inland marine coverage, commercial property or a business owner's policy, contractors E&O, and umbrella or excess liability. Client contracts can add another layer by asking for specific limits, a certificate of insurance, additional insured wording, or a waiver of subrogation.
Coverage questions that come up for drywall businesses
The most useful coverage review follows the way your business operates. Choose the situation closest to your current question, then request a quote or coverage review for the details that apply to your work.
Liability and contract requirements
Client and general contractor requirements often shape the liability review.
Review: General liability limits, completed operations, and the work described in the contract.
Bring: The contract, insurance specifications, or certificate request before requesting proof.
Employees, vehicles, and equipment
Crews, work vehicles, tools, and materials can create separate coverage questions.
Review: Workers' compensation, commercial auto, and hired or non-owned auto where applicable.
Check: Tools, rented equipment, materials in transit, and temporary jobsite storage.
Bring: Payroll, driver, vehicle, tool, and equipment details for the review.
Property, professional, and excess risks
Business property and professional work may require a closer look than a basic liability quote.
Review: Business property, equipment, business income, contractors E&O, and umbrella limits as applicable.
Check: Whether your work includes specifications, estimating, advice, or other professional services.
Bring: Your current policy, claims history, project scope, and requested limits.
Drywall contractor insurance coverage to review
Coverage should follow your actual work. The options below are common review points, but eligibility, exclusions, limits, and endorsements vary by business, state, policy form, and underwriting requirements.
Coverage to review
General Liability: May help address third-party bodily injury, property damage, personal injury, advertising injury, and completed-operations claims covered by the policy. Review the work description, limits, aggregate structure, and contract requirements.
Workers' Compensation: May help address covered work-related employee injuries and related employer obligations where applicable. State rules and classifications vary, so review the requirement for your workforce and location. The Bureau of Labor Statistics construction laborer overview provides general workplace context, not a substitute for state or policy guidance.
Commercial Auto: May cover business-owned vehicles and selected business-use exposures, subject to the policy. Review work vans, pickups, trailers, hired vehicles, non-owned vehicles, drivers, and the way materials are transported. For a closer look, review commercial auto insurance for business vehicles. Vehicle coverage does not automatically cover every tool or item inside the vehicle.
Tools, Equipment, and Inland Marine: May be relevant for tools, equipment, materials, rented equipment, transit, or temporary jobsite storage. The policy needs to match what is owned, rented, moved, or left at a project location.
Commercial Property or Business Owner's Policy: An eligible business owner's policy may combine general liability and business property coverage. Review your office, equipment, inventory, business personal property, and potential business-income exposure rather than assuming a BOP fits every operation. Learn more about business owner's policy coverage before deciding whether that structure fits the operation.
Contractors E&O or Professional Liability: May be relevant when the business provides professional services, specifications, estimating, advice, or other work where a client alleges financial loss from an error or omission. Review professional liability and E&O insurance as a separate question. It is not a substitute for general liability and does not automatically cover the cost of correcting defective work.
Umbrella or Excess Liability: May provide additional liability limits above selected underlying policies. Review the required underlying limits, covered policies, exclusions, and contract requirements before relying on an excess layer.
Boundaries to confirm
Employee injury: General liability generally is not the policy used for covered employee work injuries. Review workers' compensation and employer obligations separately.
Tools and materials: Commercial auto generally addresses the vehicle, not every tool, piece of equipment, or material inside it. Review tools, equipment, cargo, and inland marine options separately.
Workmanship: The cost to correct your own defective work may be excluded, while resulting damage or a professional allegation may be treated differently under the policy. The facts and policy form matter.
Certificates, additional insured requests, and subcontractor requirements
A certificate of insurance shows that certain coverage is reported to exist at the time the certificate is issued. It is not the policy itself and does not change the policy's terms. A contract may also ask for additional insured status, a waiver of subrogation, primary and noncontributory wording, specific limits, or a particular aggregate structure.
Before sending proof, compare the request with the policy and the contract. A certificate holder is not automatically an additional insured, and a note typed onto a certificate cannot create coverage that the policy does not provide. OSHA's construction safety resources provide general workplace context, but your policy, endorsements, and contract control the actual insurance requirement.
If you need help with the documentation itself, Dream Assurance offers certificate of insurance support. Bring the contract, insurance specifications, requested wording, deadline, and certificate-holder information so the request can be reviewed in context.
How the work you do changes the coverage review
Drywall businesses do not all operate the same way. A company that installs drywall in new commercial construction may have different questions than a small repair contractor, remodeler, finisher, or business that uses subcontractors across several jobsites.
Operational detail
Why it matters
Details to review
Installation, repair, or remodeling
The work type can affect classification, contract language, completed operations, and the hazards described to the insurer.
Typical projects, project size, work performed by your employees, and work subcontracted to others.
Commercial or multi-unit projects
Owners and general contractors may request specific limits, additional insured status, or project-related wording.
Contract requirements, project locations, aggregate requirements, and completed-operations expectations.
Employees and subcontractors
Payroll, classification, supervision, and subcontractor documentation can affect both coverage and requirements.
Employee count, payroll, certificates from subcontractors, written agreements, and who controls the work.
Vehicles, tools, and materials
Vehicle use, tools, equipment, and materials can fall under different policy sections or require separate coverage.
Vehicle list, driving radius, tool values, rented equipment, transit, and storage at or away from the jobsite.
If the work includes removal or disturbance of lead, asbestos, mold, or other pollutants, bring that scope to the review. These exposures may involve exclusions, endorsements, or separate coverage questions. Government construction-safety resources can provide general jobsite information, but they do not determine the terms of an insurance policy.
What affects drywall contractor insurance cost
There is no reliable universal price for drywall contractor insurance. A quote depends on the operation being insured, the coverage limits requested, the business location, and the policy terms available for that risk.
Work type and project mix: Installation, finishing, repair, remodeling, commercial work, and demolition-adjacent work can present different underwriting questions.
Revenue and payroll: Annual revenue, payroll, employee classifications, and subcontractor use help describe the size and structure of the business.
Vehicles and driving: Vehicle type, ownership, driver history, mileage, radius, and material transport can affect commercial auto review.
Tools, equipment, and property: The value, ownership, location, transit, and rental status of tools and equipment can change the coverage needed.
Limits, deductibles, and contract terms: A client or general contractor may request specific limits, endorsements, or proof-of-insurance wording.
Claims and prior coverage: Loss history, prior policy details, gaps in coverage, and renewal timing can affect the review.
To compare options meaningfully, gather your current policy, renewal date, work description, revenue, payroll, employee and subcontractor details, vehicle list, tool and equipment values, claims history, and any contract or certificate request.
What to gather before requesting a quote
A complete starting point helps an agent understand the business instead of treating it like a generic contractor account.
Business and work details
Business identity: Legal business name, operating locations, years in business, ownership, and the states where work is performed.
Work performed: Installation, finishing, repair, remodeling, commercial work, residential work, demolition-adjacent work, and any environmental or specialty scope.
People and payroll: Employee count, payroll, job classifications, subcontractor use, written agreements, and certificates collected from subcontractors.
Property, vehicles, and requirements
Vehicles and equipment: Vehicle list, drivers, driving radius, tools, equipment, rented items, materials in transit, and storage locations.
Current insurance: Policy declarations, limits, deductibles, endorsements, prior claims, renewal date, and any current coverage gap.
Contract requirements: Client or general contractor specifications, certificate-holder details, requested additional insured wording, waiver language, limits, and deadline.
How Dream Assurance can help review the setup
Dream Assurance is an independent insurance agency that helps businesses compare coverage options and understand what changes between policies. For a drywall operation, that may include reviewing liability, employee, vehicle, tool, property, professional, and contract-related questions together.
Dream Assurance is licensed in 30+ states. The agency serves clients in states where it and its producers hold or renew applicable insurance licenses. Coverage availability, carrier access, and policy options may vary by state, coverage type, underwriting requirements, and carrier appointment. Review the current service areas and eligibility information before assuming a specific option is available.
If you want help reviewing the details, talk with our team. Bring the policy, contract, certificate request, or renewal information that prompted your question.
I've had a fantastic experience with Dream Assurance. From the very beginning, Kurtis made the process of choosing a plan straightforward and stress-free.
If you're looking for real people that handles your needs fast then dream assurance is the way to go. Micheal Moran is probably the best insurance agent I've ever had. No matter the time or day, he finds a way to respond back. Not to mention we're in two different time zones and he works like we're in the same state. I wish I could give them more stars. Forgot to mention they'll beat any insurance rates you find!!!
Drywall contractor insurance questions
What insurance does a drywall contractor need?
A drywall contractor may need to review general liability, workers' compensation where applicable, commercial auto, tools and equipment or inland marine, commercial property or a business owner's policy, and other coverage such as contractors E&O or umbrella liability based on the work and contract requirements.
Is general liability insurance required for drywall contractors?
There is no single requirement that applies to every drywall contractor in every location. A state, client, general contractor, lender, lease, or project contract may require specific coverage or limits. Review the applicable requirement with an agent and the relevant authority before assuming a policy satisfies it.
Does general liability cover employee injuries?
Generally, general liability is not the policy used for covered employee work injuries. Workers' compensation and related employer obligations should be reviewed separately where applicable to your workforce and location.
Does commercial auto cover tools and materials?
Commercial auto generally addresses the covered vehicle and selected business-use exposures, not every tool, piece of equipment, or material inside it. Review tools, equipment, materials in transit, rented items, and inland marine options separately.
What should a drywall contractor include on a certificate of insurance?
Start with the exact certificate holder, requested limits, policy dates, and any contract language about additional insured status, waiver of subrogation, primary and noncontributory wording, or aggregate requirements. A certificate shows reported coverage and does not change the policy by itself.
Does drywall contractor insurance cover faulty workmanship?
Not necessarily. The cost to correct your own defective work may be excluded, while resulting damage to other property or a professional allegation may be treated differently under the policy. The facts, policy form, endorsements, and contract language matter.
What affects drywall contractor insurance cost?
Cost can be affected by the work performed, revenue, payroll, employees, subcontractors, vehicles, driving radius, tools and equipment, property values, location, claims history, limits, deductibles, contract requirements, and requested endorsements. A quote needs details about the specific business.
Can a drywall contractor's policy cover subcontractors?
It depends on the policy, the written agreement, how the work is classified, and the contract requirements. Subcontractors may need their own coverage and certificates. Review the agreement, certificates, and policy language before assuming another party is covered.
Headquartered in Overland Park, KS and serving clients across multiple states, our team provides straightforward guidance to help you make informed insurance decisions.
If you're comparing insurance options or reassessing your current coverage, we'll help you evaluate what you have, identify potential gaps, and find a path forward that makes sense for your situation.
Licensed In 30+ States
Headquartered in Overland Park, KS, with licensed support across the Midwest, South, Northeast, and West.
AL, AZ, AR, CA, CO, DE, FL, GA, IL, IN, IA, KS, KY, MI, MN, MS, MO, MT, NE, NV